ServicesMergers and Acquisitions
Mergers and Acquisitions in Bastrop
We help private business owners combine with, sell to or acquire another company. We find the right counterparty under strict confidentiality, then structure the deal so the cash, notes and earnouts you agree to still pay off years after closing day.
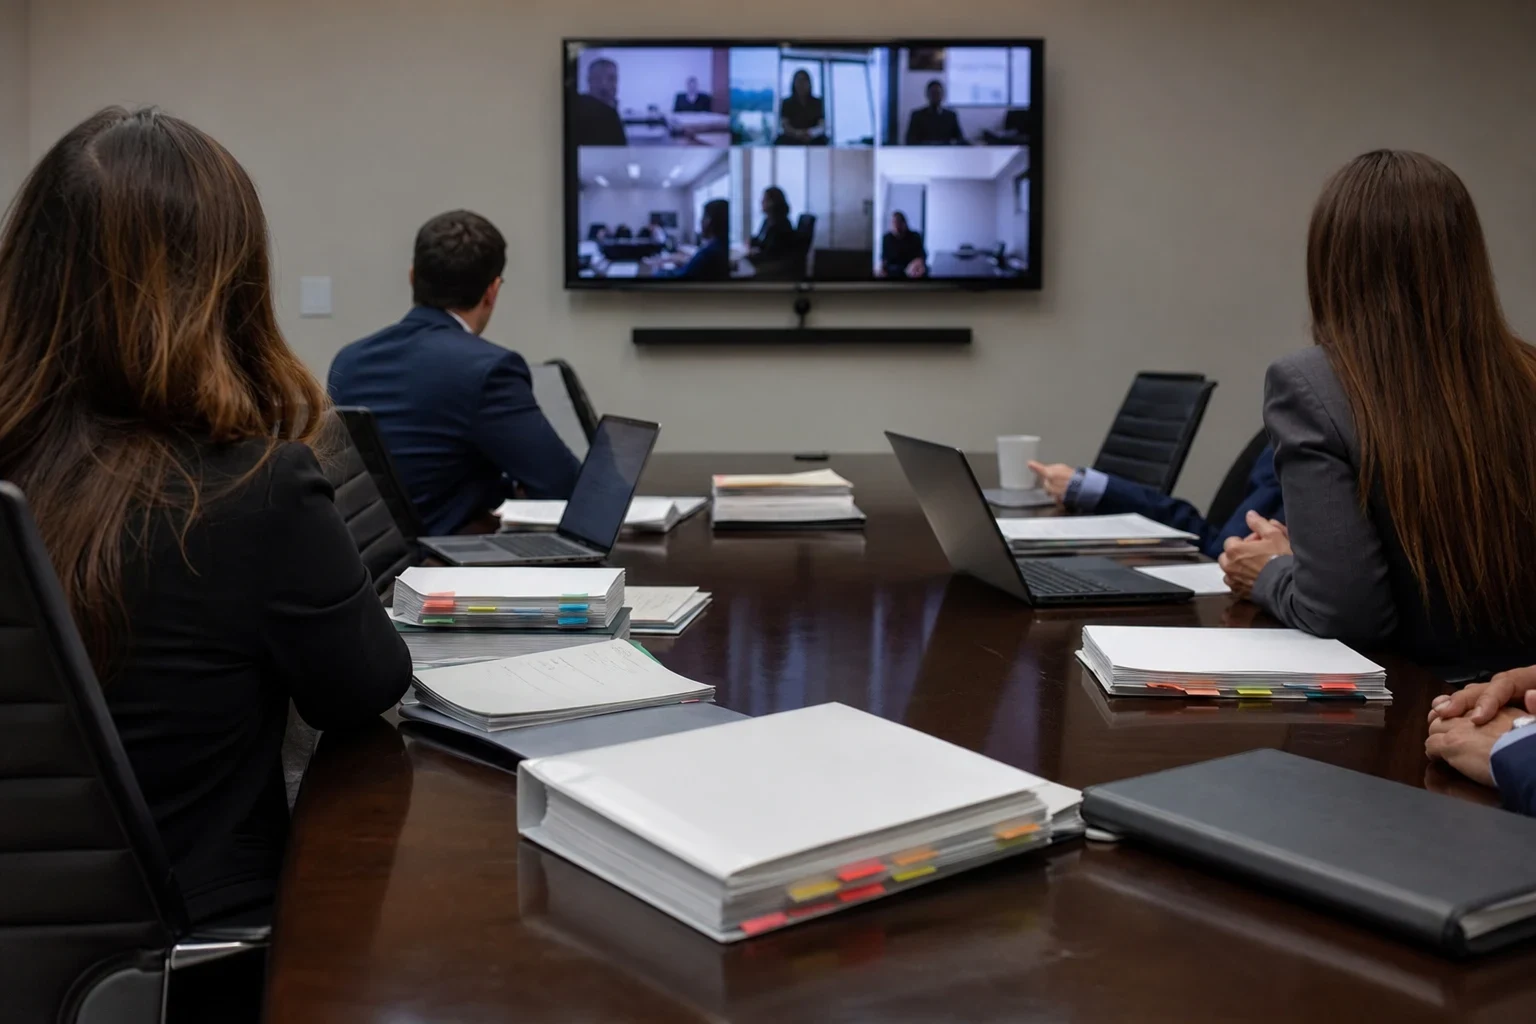
When merging or acquiring makes sense
An M&A deal is not the same as a standard listing. The counterparty tends to be strategic, such as a competitor, a supplier or a bigger regional company, and it values your customers, people or contracts for what they bring to its own business. That fit can justify a higher price, and it also comes with more complicated terms.
The top-line price seldom shows what you actually keep. A lower offer with more cash at closing can serve you better than a larger one resting on a long earnout, a weak seller note and a working capital target set too high. We split each offer into its pieces and measure what each is worth over time, not only on signing day.
We meet at our office or by phone and video with owners throughout Bastrop County and nearby towns such as Elgin and Smithville.
What our M&A work includes
- Confidential counterparty search
- We build a blind profile that describes your business without naming it. Strategic buyers or acquisition targets see details only after signing a nondisclosure agreement, so your staff, customers and competitors do not hear about it early.
- Valuation and synergy analysis
- We normalize your earnings by adding back owner perks, one-time costs and above-market rent. Then we estimate what the combination is worth to a specific buyer, because a competitor that can cut overlapping overhead may pay more than a financial buyer.
- Deal structure review
- We lay out the tradeoffs between an asset sale and a stock sale, cash at closing versus seller financing, and earnout terms tied to revenue versus profit. Each choice shifts risk and changes what reaches your bank account.
- Letter of intent and negotiation
- We negotiate the letter of intent before diligence starts, while you still have leverage. That covers the price, working capital peg, exclusivity period and your role after closing.
- Diligence and closing coordination
- We organize the data room, track document requests and keep your attorney, CPA and the buyer's lender on schedule through the purchase agreement and closing.
Signs it is time to talk about a merger or acquisition
An unsolicited offer arrived
A competitor or supplier asking to buy you is a signal of value, but a first offer is usually a test. Before answering, get a valuation so you know what the business is actually worth.
Growth is capped by capacity
If you are turning down work for lack of crews, equipment or credit, joining a larger company may let the business grow faster than you could fund alone.
A few customers carry the revenue
Heavy customer concentration lowers what most buyers will pay. A strategic buyer that already serves those accounts may see it as a reason to pay more.
You want to buy a competitor
Acquiring a rival can add market share faster than organic growth. We help you size up the target and plan how to pay for it.
The offer leans on an earnout
When much of the price depends on future results you will not control after closing, the terms need close review before you sign anything.
How we run an M&A engagement
- 1
Private consultation
We go over your goals, your timing and any offers you already have. Nothing said on the call goes further unless you approve it.
- 2
Value and positioning
We study three years of tax returns and financial statements, normalize earnings and pin down which buyers or targets are a fit. You see the value clearly before any outsider sees a figure.
- 3
Approaches under NDA
We contact a short list of qualified parties, check that they can pay and share details step by step as their interest grows.
- 4
Offers lined up together
We put each letter of intent into the same terms: cash at closing, deferred payments, how likely the earnout is to pay, tax treatment and what you owe after closing. That reveals which deal really pays more.
- 5
Diligence to closing
We handle document requests, deal with problems as they come up and keep the purchase agreement in line with the letter of intent until the money moves.
What sets the cost of an M&A deal
Putting your company on the market with us has no up-front cost. You sign no retainer and find no fee hidden in the documents, since we are paid only from a completed sale, when the seller is paid. A deal's total cost also includes outside advisors and financing, which shift with the factors below.
- Size and shape of the deal
- A stock sale carrying an earnout, an escrow holdback and a seller note needs more drafting and negotiating than a straight cash asset purchase.
- State of your records
- Accrual-based statements that reconcile with your tax returns speed up diligence. Disorganized books can prompt a buyer to commission a quality-of-earnings review, adding time and expense.
- Legal and accounting advisors
- Both sides cover their own lawyers and tax advisors. Those bills rise with every contract, lease and employee agreement that has to be reviewed.
- Lender conditions
- Deals funded by a lender add appraisals, underwriting and closing conditions. Our acquisition financing guidance helps buyers prepare for each of them.
Questions about mergers and acquisitions
Something not covered here? (512) 551-1187
How does a merger differ from selling my business?
A sale transfers ownership, and you typically step away after a transition. A merger joins two companies, and owners may hold equity or a role in the combined firm. With small private companies, most so-called mergers are actually purchases by the bigger party. We tell you which kind an offer really is.
How is the deal kept confidential?
Buyers start with a blind profile that leaves out the name, address and anything identifying. Complete financials go only to parties who sign a nondisclosure agreement and prove they can pay. The most sensitive material, such as customer lists and payroll, comes last, usually once a letter of intent is signed.
Is an earnout worth taking?
An earnout can bridge the gap between your price and the buyer's, but it pays only if future targets are hit while someone else runs the company. We check the metric, the length and who makes the decisions behind it. For a seller, a shorter earnout based on revenue is generally safer than one based on net profit.
Which is better, an asset sale or a stock sale?
Buyers tend to want asset sales for the stepped-up tax basis and to leave old liabilities behind. Sellers tend to want stock sales for simpler taxes. The answer turns on your entity type and contracts, so we sort it out with your CPA before you sign a letter of intent.
Can you help me buy another company instead?
Yes. We help buyers locate and assess targets, go through the seller's financials and negotiate the terms. First-time buyers can find the basics on our Buy a Business page.
Know what an offer is really worth
Before you answer a buyer or approach a target, get a clear read on value and terms. The first conversation is free and stays confidential.